Cashout workflow
Caspero withdrawals in Australia: cashout, verification and complaint context
 Available in AU
A Caspero withdrawal should be understood as a sequence rather than a single payout timer: submit the request, confirm the available withdrawal route, complete any account or identity checks that are requested, wait for the operator-side review, then wait for the payment provider to deliver the funds. Caspero’s current public site lists withdrawal support across cards, e-wallet style services and cryptocurrencies, but it does not establish Australian-specific payout limits, fees or processing windows for this guide.
For that reason, exact time and limit figures should be read from the logged-in cashier at the moment of withdrawal. Recent complaint records are useful as case evidence, but they do not prove a universal Caspero payout pattern.
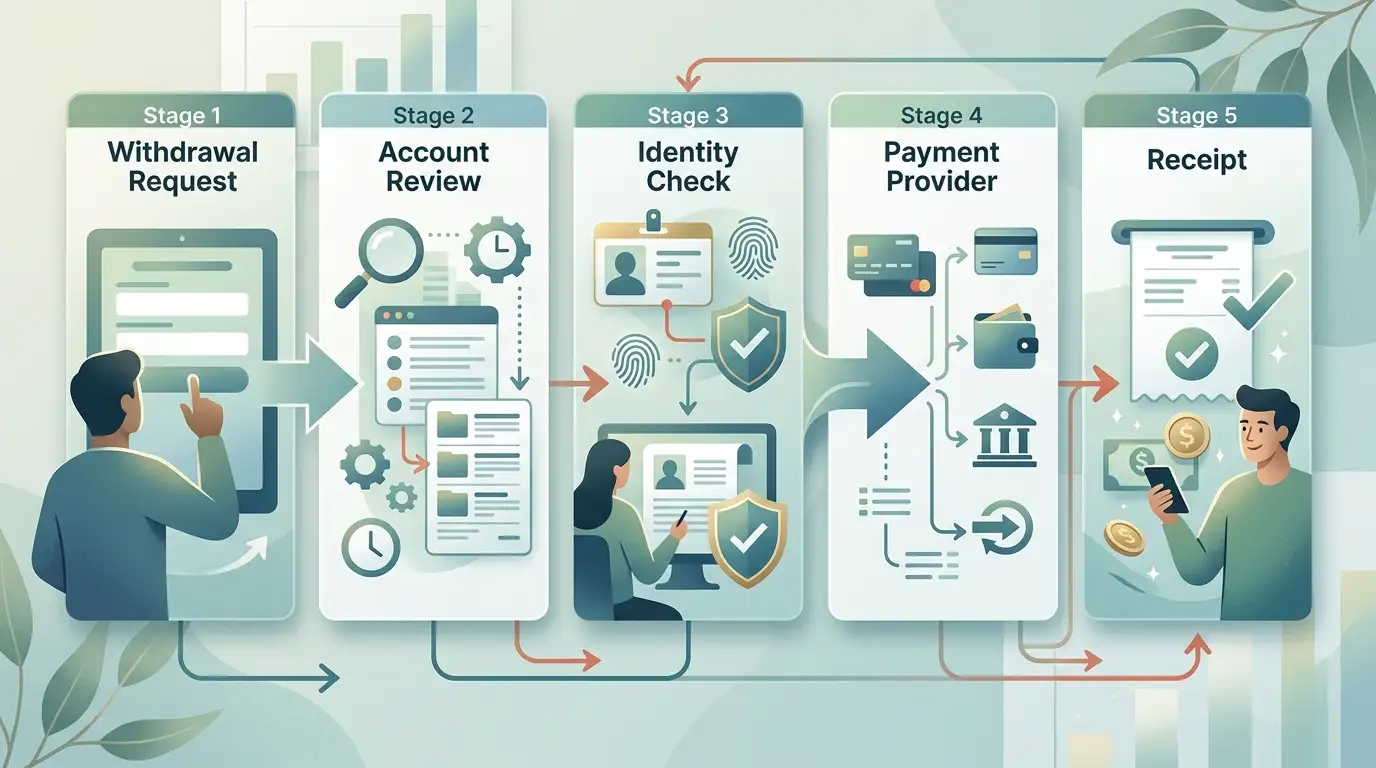
Table of Contents
- The withdrawal process is easier to judge when it is split into stages
- What is verified and what still needs a live cashier check
- Separate operator review time from payment-provider time
- Verification can intersect with withdrawals without defining every cashout
- Recent complaints are evidence of individual cases, not a payout benchmark
- How to read a withdrawal complaint without overgeneralising it
- Prepare the evidence you would need if a cashout stalls
- Payment method choice can affect what happens after approval
- Australian legal context is separate from the cashout workflow
- How to assess a Caspero withdrawal before and after submitting it
The withdrawal process is easier to judge when it is split into stages
Caspero’s public material describes withdrawals as available through several payment routes, including cards and cryptocurrencies. The practical Australian question is not simply whether withdrawals exist, but what happens between clicking withdraw and receiving money.
- Request. Choose an available withdrawal method and enter the amount shown as permitted in the current cashier.
- Account review. The operator can check account status, transaction history or other conditions before releasing a payment.
- Verification. Identity or account checks may be requested. The current public material does not provide a reliable Australian document list or a guaranteed verification time.
- Operator release. Once approved, the payment leaves the operator-side queue.
- Payment-provider completion. A card issuer, wallet, bank or blockchain then has its own delivery or settlement process.
This staged view is useful because a delay can sit in different places. A payment-provider delay is not the same thing as an operator review, and a verification request is not itself evidence that a withdrawal has been refused.
What is verified and what still needs a live cashier check
Caspero currently lists Visa, Mastercard and cryptocurrency payments at brand level. Its public page also advertises withdrawal availability and publishes euro-denominated examples. Those examples are not used here as Australian terms because the page is aimed at Australian readers and the exact transaction conditions are high-change details.
Before submitting a cashout, use the cashier as the current source for the method, account currency, minimum, maximum, any fee notice and any processing message. If the cashier differs from an older review or marketing page, the live account interface is the more relevant operational evidence.
Cards
Listed at brand level
Crypto
Supported at brand level
AU limits
Check live
AU fees
Check live
Payout time
No universal AU time stated here
KYC documents
No exact list published here
Separate operator review time from payment-provider time
A common source of confusion is treating the entire cashout period as one number. In practice, two separate clocks can matter. First, the casino decides whether a request can be released. Second, the receiving payment rail completes the transfer.
That distinction helps when support gives an update. If the withdrawal is still pending inside the Caspero account, the issue is likely still within the operator-side process. If Caspero says a payment has been sent, ask for the transaction reference that is appropriate to the method and then contact the receiving provider if necessary.
For card payments, this can mean checking whether the bank can locate the incoming transaction. For crypto, it can mean checking whether a transaction hash exists and whether the destination network matches the withdrawal request. For an e-wallet or bank transfer, the relevant reference can differ. Do not invent a tracking method that the payment route does not actually use.
Verification can intersect with withdrawals without defining every cashout
Caspero’s current public site discusses identity verification in its support material, so verification can be part of account handling. However, no current authoritative Caspero source checked for this page provides a complete document list, guaranteed review time or Australia-specific KYC sequence. Those details are therefore not presented as fixed rules.
If verification is requested, follow the instructions shown in the account or sent through the verified support channel. Upload only what the current request asks for, use clear copies, and keep a record of the request and submission date. If the request changes, ask support to explain what remains outstanding.
The broader registration and verification guide explains the difference between Caspero-specific evidence and Australian customer-identification context. The withdrawal page keeps the focus on how verification affects a pending cashout.
Do not assume a fixed KYC list
Passport, licence, address and payment-source documents are common industry examples, but this page does not present them as Caspero requirements unless the current account flow specifically requests them.
Recent complaints are evidence of individual cases, not a payout benchmark
Current AskGamblers complaint records include multiple 2026 Caspero cases involving delayed or cancelled withdrawals. Several are marked resolved after later payments or account updates, while one large withdrawal dispute remains marked unresolved. That mix is useful because it shows why complaint status matters as much as the original allegation.
A complaint begins as a player’s account of what happened. A resolved label shows that the case later reached a closure accepted by the complaint platform, while an unresolved case shows that the dispute did not reach that kind of closure. Neither status proves how every other withdrawal will behave. The case date and final outcome should always be read together.
For a broader evidence review, see the site’s complaints and trust page. The current complaint archive is also available directly at AskGamblers.
How to read a withdrawal complaint without overgeneralising it
| Evidence in a complaint | What it can show | What it cannot prove |
|---|---|---|
| Date and amount | The scale and timing claimed in that case | The normal limit or timing for all users |
| Support messages | What the player says support communicated | A platform-wide service standard |
| Verification request | That KYC affected that case | That every withdrawal requires the same documents |
| Resolved status | The complaint platform recorded a later resolution | That the original delay did not occur |
| Unresolved status | The dispute was not closed as resolved | That all Caspero payouts fail |
This framework is more useful than counting negative headlines because it forces the reader to separate the initial allegation, the operator response and the final case status.
Before submitting a withdrawal
- Confirm the account currency and available cashout method.
- Read the current minimum, maximum and any fee notice.
- Check whether bonus conditions still affect withdrawable balance.
- Make sure account details match the payment route.
- Save the request confirmation or reference.
Prepare the evidence you would need if a cashout stalls
The best time to prepare for a dispute is before one exists. Record the withdrawal date, amount, method and on-screen status. If the status changes, capture that change. If support provides a reference number, keep it with the conversation date and the channel used.
Do not post unredacted bank statements, identity documents, wallet addresses linked to personal information or account screenshots containing balances and personal data on a public complaint site. Share sensitive documents only through the operator’s authenticated process or another channel you have verified.
If a payment has been marked sent, ask what evidence can be used to trace it. If it is still pending, ask which review stage remains incomplete. These are more precise questions than asking only when the money will arrive, and they create a clearer record if the case later needs escalation.
Payment method choice can affect what happens after approval
The payment methods page explains Caspero’s brand-level card and crypto support and why Australian availability must be checked in the cashier. That matters for withdrawals because the receiving route can change what evidence is available once Caspero says funds have been released.
A blockchain withdrawal can often be traced with an on-chain transaction identifier once sent. A card refund or card payout can depend on issuer processing and may use a different reference. A bank or wallet transfer can have another settlement path again. The method therefore affects troubleshooting even when the operator-side review is identical.
Do not choose a deposit method only for speed claims. Check whether the same route can receive withdrawals and whether the account terms require return to the original method where possible.
Australian legal context is separate from the cashout workflow
Australia’s Interactive Gambling Act restricts providers from offering online casino services to people in Australia, and no Australian local licence has been verified for Caspero. This does not change the practical need to document an existing withdrawal request, but it is relevant when assessing the overall service and available local regulatory pathways.
The licence and legal context page covers that issue in detail. This withdrawal guide does not label Caspero as holding an Australian licence and does not treat an offshore licence claim as an Australian authorisation.
How to assess a Caspero withdrawal before and after submitting it
Before the request, confirm the live cashout method, currency, limit, fee notice and any account condition shown in the cashier. After submitting, distinguish a pending operator review from a payment that has already been released to the receiving provider. If verification is requested, follow the specific current request rather than relying on a generic document checklist. And when reading complaints, use each case as case evidence with its final status, not as a universal payout timer for Caspero. For the wider product and regulatory context, return to the Caspero Australia review.
Created by the ”Caspero Casino” editorial team.